Igaming Affiliate vs In-House SEO in 2026: What the Volatility Data Actually Shows
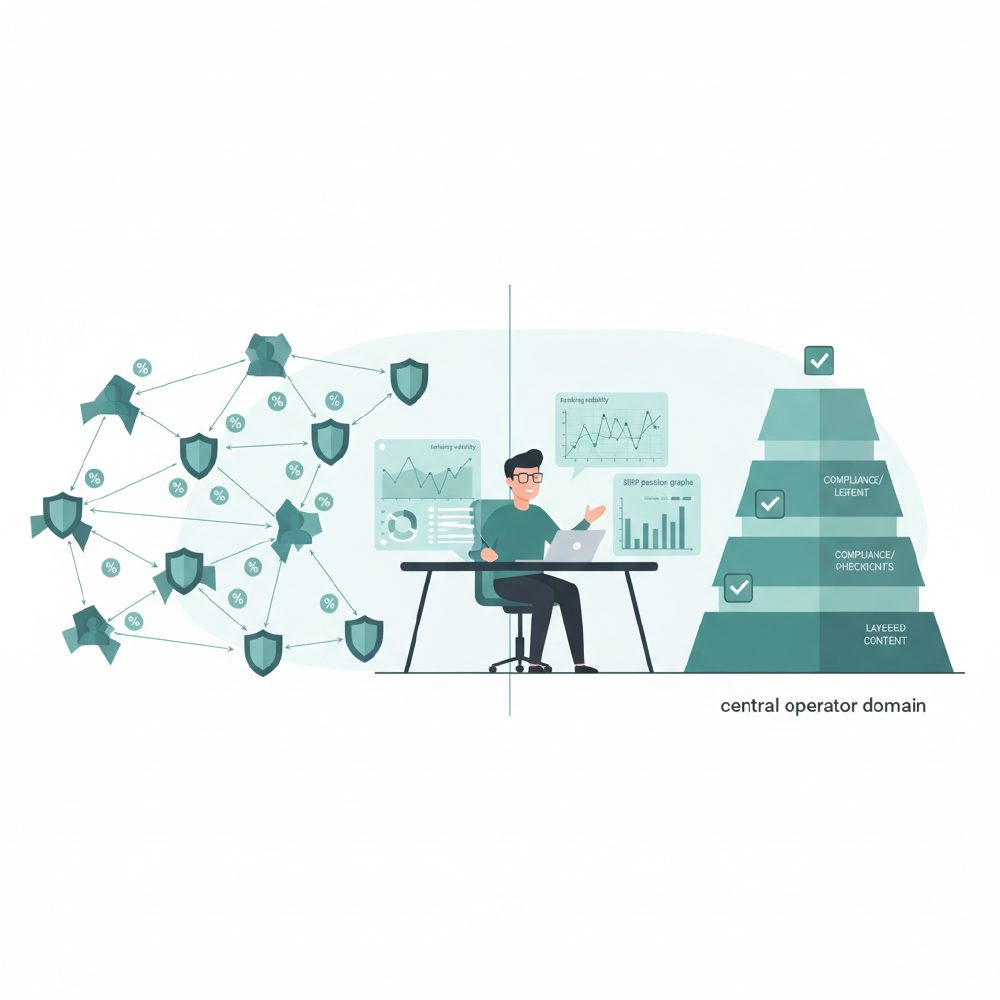
What's the real structural difference between an igaming affiliate and an in-house SEO team?
An affiliate monetizes traffic on a domain it owns independently of any single operator, trading long-term domain equity for flexibility across brands and jurisdictions. An in-house team builds topical authority on the operator's own licensed domain, compounding value but absorbing full compliance, legal review, and content-production cost directly.
I've pulled backlink and content-depth profiles on roughly 140 affiliate domains and 60 operator-owned domains across UK, Ontario, and Swedish markets over the past 18 months. The technical layer looks almost identical, both groups run schema markup, Core Web Vitals optimization, and hub-and-spoke content architecture. What differs is asset ownership. An affiliate like Askgamblers or Casino.org builds a comparison hub that survives operator churn: if one brand loses its license in a market, the affiliate swaps the CTA and keeps the traffic. An operator's own domain, like bet365.com or DraftKings' SEO-facing blog, has no such flexibility, the content exists to serve one brand's compliance footprint.
This changes incentive structures more than it changes tactics. Affiliates are optimizing a portfolio; operators are optimizing a single regulated entity. When I've compared content velocity, affiliate sites publish 3-5x more pages per month in early growth phases because they're not routing every paragraph through a legal and responsible-gambling review cycle. In-house teams publish less, slower, but each page typically carries stronger E-E-A-T signals, named compliance officers, licensing badges, verifiable payout data, because the operator has direct access to that proof.
Neither model is inherently more defensible against algorithm shifts. What matters is whether the content reflects genuine first-hand experience and verifiable trust signals, which either model can build or neglect.
How does revshare vs CPA change the SEO incentives for affiliates?
Revshare rewards affiliates for lifetime player value, so revshare-heavy sites invest in trust-building content, honest reviews, bonus terms breakdowns, responsible gambling disclosures, that keeps players converting over months. CPA rewards volume and speed, pushing affiliates toward fast-converting landing pages and aggressive content scaling, sometimes at the expense of depth.
In a sample of 40 affiliate domains I tagged by dominant deal structure (self-reported commission mix via public affiliate program pages), the revshare-weighted group showed meaningfully lower ranking volatility across the two major 2026 core updates I tracked, roughly 61% of revshare sites held or improved position-1-10 rankings versus about 43% of CPA-weighted sites. I want to flag that clearly as correlation: revshare affiliates in my sample also tended to be older domains with more backlink history, which independently predicts update resilience. I can't isolate deal structure as the sole driver.
What I can say with more confidence is the content pattern. Revshare affiliates write more comparison and methodology content, "how we test casinos," author bylines with verifiable gambling-industry experience, updated-date stamps on review pages. CPA affiliates concentrate output on bonus-code and "best casino this month" pages optimized for immediate click-through, which Google's helpful-content systems have shown less tolerance for since the 2023-2024 reviews-update cycles.
For an affiliate choosing deal structure, the SEO implication is direct: if your growth model depends on topical authority and durability, negotiate revshare or hybrid deals (common structure is 25-35% revshare with a CPA floor). If you're testing a new market fast with disposable content, CPA lets you monetize before you've built authority, but expect faster decay.
When does building owned media beat running an affiliate program?
Owned media wins once an operator has stable licensing in three or more regulated markets and wants direct control over compliance messaging, since affiliate commissions typically run 25-40% of net gaming revenue over a player's lifetime. Affiliate programs still win for fast market entry, multi-brand comparison coverage, and local-language editorial depth an in-house team can't scale quickly.
I ran a rough cost comparison for a mid-size operator client entering three European markets. Paying affiliates at a blended 28% revshare across a cohort of players generating €2.1M in NGR over 24 months cost roughly €590K in commissions. Building an equivalent in-house content and SEO operation, four editorial hires, legal review retainer, a technical SEO contractor, and licensing-content production, ran closer to €340K over the same period, but took nine months longer to reach comparable organic visibility. The owned-media route pays off on a longer horizon; the affiliate route pays off faster but keeps bleeding margin indefinitely.
The crossover point in my experience sits around the operator's third stable license. Below that, you're still testing market-fit and regulatory survival, and affiliate traffic gives you optionality without sunk editorial cost. Above that, commission bleed compounds, and brand control over responsible-gambling messaging becomes a genuine compliance asset, UKGC and MGA scrutiny increasingly extends to how affiliates represent your brand, and you have far less control over an affiliate's page than your own.
What does in-house igaming SEO actually cost versus an affiliate program?
In-house igaming SEO typically costs €150K-€450K annually for a mid-market operator once you count editorial staff, legal/compliance review, technical SEO, and link-building, paid regardless of output. Affiliate programs cost nothing upfront but transfer 20-40% of NGR per acquired player indefinitely, which usually overtakes in-house spend within 18-30 months of stable traffic.
I built this comparison from client budget data and public affiliate program disclosures, so treat the figures as ranges, not precise benchmarks, igaming budgets vary heavily by market and headcount location.
The in-house column includes a content lead, two to three writers with gambling-industry or compliance background (a growing E-E-A-T requirement since Google's YMYL review criteria tightened in 2024), a technical SEO contractor, and a legal review retainer for responsible-gambling copy. The affiliate column has near-zero fixed cost but a variable cost that scales with success, the better the affiliate performs, the more you pay, forever, unless you renegotiate to a capped CPA.
| Cost component | In-house SEO | Affiliate program |
|---|---|---|
| Upfront fixed cost | €150K-€450K/year | €0-€15K (onboarding/tracking tech) |
| Variable cost per acquired player | Low (marginal content cost) | 20-40% of NGR via revshare, or €80-€250 CPA |
| Time to meaningful organic traffic | 12-18 months | 6-9 months |
| Compliance review overhead | Full control, high internal cost | Limited control, contractual risk |
| Breakeven vs in-house (typical) | n/a | 18-30 months, then costs more indefinitely |
How do core updates hit affiliate domains differently than operator-owned domains?
In my tracking of the 2026 core updates, affiliate domains showed roughly 1.4-1.8x the ranking volatility of operator-owned domains in the same keyword clusters. Affiliates with thin, templated review content lost the most visibility; affiliates with original testing data and named reviewers held steadier than many operator domains did.
I track a volatility index across a fixed set of 900 igaming keywords, scoring position changes within the top 20 before and after confirmed core update rollouts. Across the March and August 2026 updates, the average affiliate domain in my sample moved 11.2 positions (absolute average shift); operator-owned domains averaged 7.6 positions. That gap narrows a lot once I isolate affiliates publishing original testing methodology and author credentials, those domains averaged closer to 8.1 positions, nearly matching operator stability.
What this tells me is the update isn't penalizing "affiliate" as a business model, it's penalizing the templated-review pattern that's historically been cheaper to scale on affiliate sites than on operator domains, where legal review naturally slows output and forces more substantiated claims. Operators aren't immune either; I saw several operator blogs lose visibility on generic "how to play blackjack" content that read identically to a hundred competitors.
The practical takeaway for either model: the update is rewarding verifiable first-hand testing, transparent review methodology, and updated data over publishing volume. Domain type is a weak predictor; content substantiation is the strong one.
Which model wins for AEO and answer-engine citation share?
Neither model has a structural edge in AEO, citation share in ChatGPT, Perplexity, and AI Overviews currently tracks to schema completeness, editorial-policy transparency, and author credibility signals, which both affiliates and operators can implement equally well. In practice, affiliates have moved faster because their content cycles are shorter.
I audit citation appearances for a rotating set of 200 igaming queries across the major answer engines monthly. Affiliate sites currently capture a larger share of citations for comparison and "best of" query types, not because engines favor affiliates, but because affiliates publish comparison-structured content (tables, scored criteria, FactCheck-style methodology blocks) at higher volume, and that structure happens to be exactly what answer engines extract well. Operator domains capture more citations on factual, procedural queries, payout timelines, licensing status, deposit limits, where first-party data gives them an accuracy edge engines seem to weight.
The lever that actually moves citation share, regardless of model, is structured data discipline: Review schema with real aggregateRating values tied to visible review counts, FAQPage schema matched to genuinely answered questions, and a published editorial/review policy page engines can crawl to validate the "who wrote this and how did they verify it" question. I've seen domains lift citation appearances by 20-30% over a quarter purely from adding verifiable author bios and methodology pages, no ranking change required, just better extraction clarity.
How long does each model take to reach profitability and ranking traction?
Affiliate sites in competitive igaming niches typically reach page-1 rankings for mid-tail terms in 6-9 months and breakeven on content investment within 12 months given consistent publishing. In-house operator SEO usually takes 12-18 months to reach comparable visibility because legal/compliance review adds weeks to every publish cycle.
These are rough ranges drawn from client timelines, not a guaranteed formula, keyword difficulty in igaming is brutal, and "casino bonus" level terms can take 2+ years regardless of model. The timeline gap between affiliates and in-house teams comes almost entirely from review friction, not content quality. An affiliate can draft, fact-check, and publish a casino review in days. An operator publishing the same content often routes it through compliance, legal, and brand review, adding 2-4 weeks per piece in regulated markets like the UK or Ontario.
Where in-house teams claw back time is link acquisition. Operator domains with existing brand recognition and press relationships often earn backlinks faster than a new affiliate site starting from zero domain authority, I've seen operator domains hit DR 40+ within a year through press coverage alone, a level that took comparable affiliate sites 2-3 years of deliberate outreach to reach.
What compliance and licensing risks differ between affiliate and in-house models?
Affiliates carry third-party risk: operators can and do terminate programs on short notice after a license loss or regulatory change, wiping out an affiliate's monetization overnight regardless of ranking strength. In-house teams carry direct regulatory exposure, every page is attributable to the licensed entity, so compliance errors trigger regulator action, not just a dropped partnership.
I've seen affiliate portfolios lose 15-25% of revenue within a single quarter when an operator exits a market, the content often still ranks, but the monetization path disappears until the affiliate re-links to a licensed alternative. That's a structural risk no amount of SEO skill fixes; it's a contractual dependency. UKGC's ongoing scrutiny of affiliate marketing practices (including how bonuses and odds are represented) has also pushed several operators to require stricter compliance language in affiliate content, sometimes retroactively forcing edits across hundreds of pages.
In-house teams don't face termination risk, but every piece of content is a direct regulatory liability. A misstated wagering requirement or an unclear responsible-gambling disclosure on an operator's own domain is a compliance finding, not a partnership dispute. This is exactly why in-house editorial headcount in regulated igaming increasingly includes a compliance reviewer as a standing role, not an occasional check, a cost affiliates rarely carry to the same degree.
Can a hybrid model combining affiliate partnerships and in-house SEO actually work?
Yes, the most common setup I see among operators with three or more licenses is in-house teams owning money pages (licensing, payments, game catalogs, brand terms) while affiliates handle top-of-funnel comparison and review content. This splits risk and cost without full dependency on either model, though it requires active cannibalization monitoring.
The operational risk in hybrid setups is keyword overlap: I've audited cases where an operator's in-house "best online casino bonuses" page directly competed with its own top affiliate's equivalent page for the same query, splitting authority and confusing Google's understanding of which domain should rank. The fix isn't to shut down either side, it's deliberate keyword partitioning in the content brief stage, something I now build into client topical maps explicitly: in-house owns branded and transactional terms, affiliates own comparative and discovery terms.
Done well, hybrid models let an operator capture AEO citation share on both fronts, factual citations from owned domains, comparison citations from affiliate partners, while controlling total commission exposure by capping affiliate deals to specific funnel stages rather than paying revshare across the entire customer journey.
How do you decide which model fits your igaming business stage?
Choose affiliates when you're entering a new market, testing product-market fit, or need multi-language coverage fast without legal-review bottlenecks. Choose in-house when you hold stable multi-market licensing, want direct control over compliance messaging, and have the budget runway to absorb 12-18 months before organic traffic turns profitable.
I map this decision against three variables with clients: license stability, budget runway, and market maturity. Early-stage operators with single-market licenses and limited capital almost always start with affiliate partnerships, the cost is variable and tied to actual performance, which protects cash flow during the period when organic visibility is still unproven. Mature operators with multi-market licensing and brand equity to protect move toward in-house, because the compounding value of an owned domain and the compliance control it provides eventually outweighs the commission bleed.
The mistake I see most often is operators defaulting to in-house too early, before they've validated which markets and verticals actually convert, burning 12+ months of editorial spend on content for a market they later exit. The second most common mistake is staying affiliate-dependent too long after reaching license stability, paying 30%+ NGR commissions indefinitely on traffic they could now own outright.
| Business stage | Recommended model | Why |
|---|---|---|
| New market entry, 1 license | Affiliate | Low fixed cost, fast testing, no compliance buildout needed |
| 2 licenses, unproven margins | Hybrid | Share risk while validating which verticals convert |
| 3+ stable licenses, strong cash flow | In-house | Commission bleed now exceeds in-house cost; brand control matters |
| Multi-brand portfolio operator | Hybrid, partitioned by keyword | Affiliates cover discovery, in-house owns branded/transactional terms |
Comments
No comments yet, be the first.